How to Get Insurance to Pay for a Roof Replacement
Where Your Home Comes First
Homeowners policies generally cover roof damage caused by a sudden event: wind, hail, a fallen tree, a storm. They generally do not cover a roof that wore out.
That distinction is the whole game. Almost every denial comes down to a carrier deciding your roof failed from age rather than from weather.
Here is how the process actually runs, and what to do when it goes against you.
Step 1. Document the date
Insurance claims are tied to a specific event on a specific date.
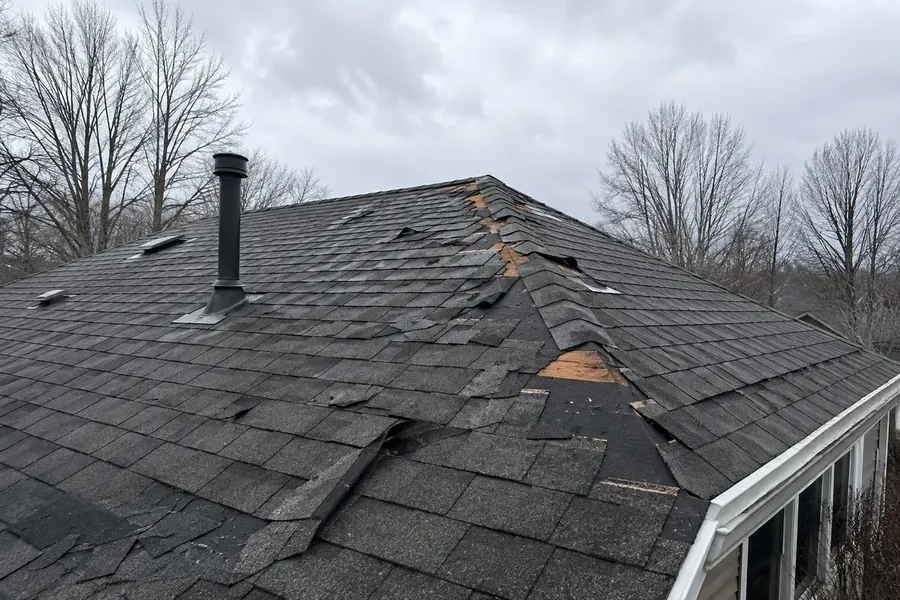
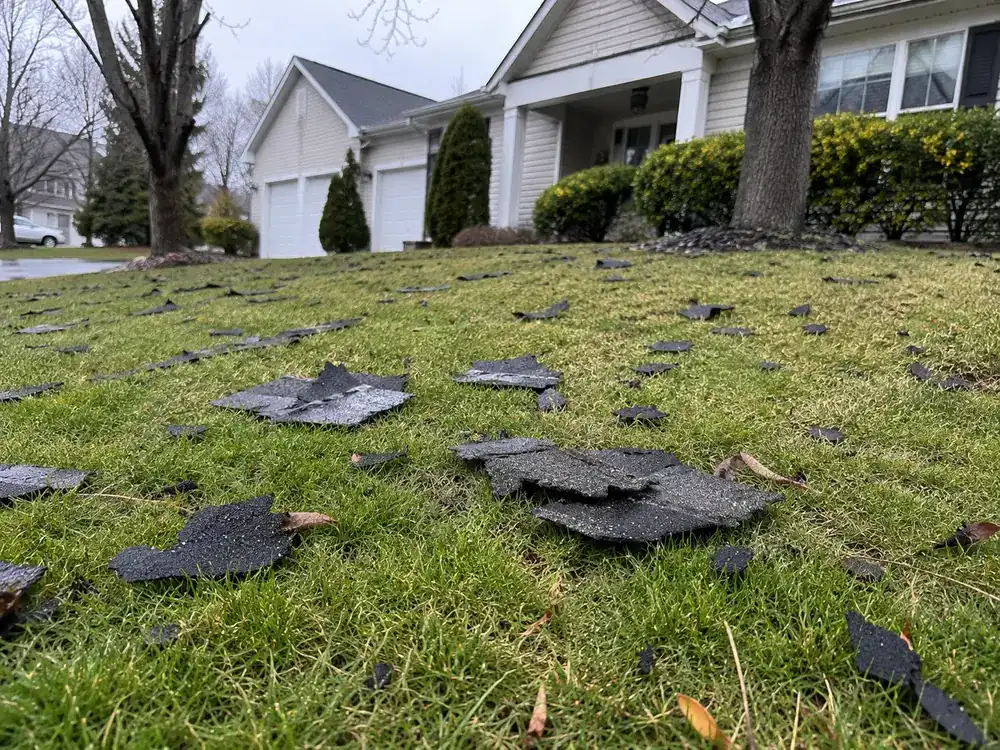
If a storm came through on the 7th and you file on the 20th, you need to establish that the 7th is when the damage happened. Note the date. Save any local news coverage of the storm. Photograph what you can see from the ground, including debris in the yard.
One Williamsport homeowner went out the morning after a February windstorm to pick up shingles that had blown into her yard. Those photos are exactly what an adjuster wants to see.
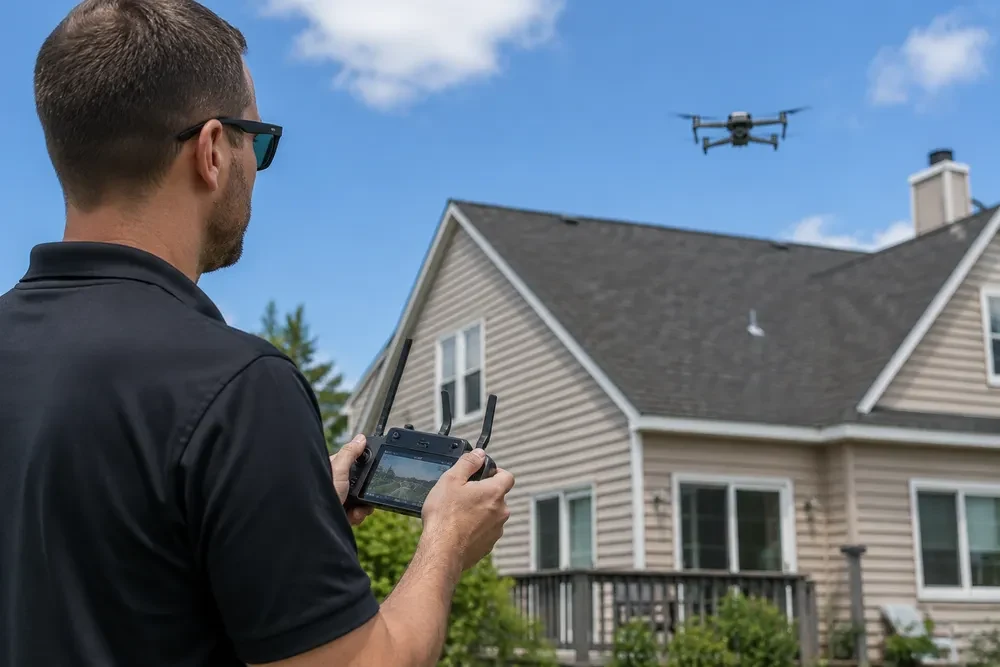
Step 2. Get the roof inspected before you call the carrier
This order matters more than most people realize.
If you file first, the carrier sends their adjuster, and their assessment becomes the starting position for everything that follows. If you have a contractor's documented inspection in hand first, you are negotiating from evidence rather than reacting to theirs.
A proper inspection means someone on the roof, not a look from the driveway. Damage that decides a claim, lifted shingles, bruised granules, cracked flashing, is not visible from the ground. One customer put it plainly: what looked fine from the ground was actually in pretty bad shape up close.
Our inspection is free and we photograph everything.
Step 3. Know what kind of policy you have
Two kinds, and the difference can be thousands of dollars.
Replacement Cost Value (RCV).
Pays what it costs to replace the roof today, minus your deductible. Usually paid in two parts: an initial check, then the remainder once the work is done.
Actual Cash Value (ACV).
Pays replacement cost minus depreciation. On a fifteen-year-old roof, depreciation can be most of the value.
Check your declarations page before you file. If you have ACV on an older roof, you may be looking at a much smaller payout than you expect, and that changes whether filing is worth it against your deductible.
Step 4. Be careful what you say
Adjusters ask when you first noticed the problem. It is a reasonable question and it is also the question that sinks claims.
"I've been meaning to get that looked at for a while" tells a carrier the damage predates the storm. Answer accurately and specifically. If you noticed it after the storm, say that. If you genuinely do not know, say that instead of guessing.
Do not speculate about causes. Do not agree that the roof is "getting old." Describe what you observed and when.
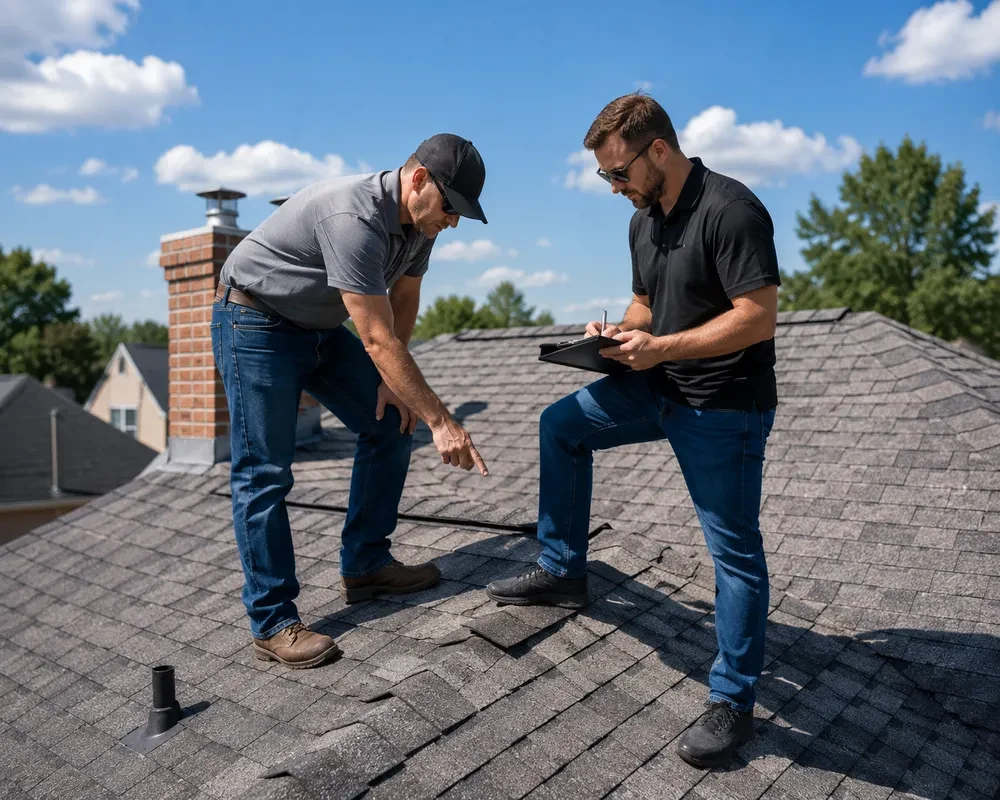
Step 5. Be there for the adjuster's visit
Have your contractor there too.
An adjuster is doing a fast assessment on one of many properties that week. A roofer who has already been on your roof can point to specific damage, which is different from hoping it gets noticed.
We attend every adjuster inspection on our customers' homes
, and if the carrier sends someone out more than once, we're there each time. It isn't an upsell or a scheduling favor. It's the single most useful thing a contractor can do during a claim, and we treat it as standard.
What to do when the claim is denied
Denials are not final. They are a position.
Denied claims are a large part of our work. We review what the adjuster found, document what's actually on the roof, and take it back to the carrier with evidence.
One of our customers was told outright by his insurer that there was no damage to his roof. We documented what was actually there, communicated directly with the carrier, and the claim was reopened. His full roof and his shed roof were both approved. In his words, without that he would have been stuck paying out of pocket for something that should have been covered.
That is one homeowner's experience, not a promise about yours. Every claim is different and plenty of denials are correct. What we can tell you is that a denial is worth a second look before you accept it.
What you can do:
Request the adjuster's report in writing.
You are entitled to the reasoning.
Get an independent assessment.
A documented contractor inspection that contradicts the adjuster's findings is the basis of any appeal.
Ask for a re-inspection.
Carriers will send someone back, particularly with new documentation.
File a complaint with your state insurance commissioner
if you believe the denial was improper. In Maryland that is the Maryland Insurance Administration. Carriers respond to those.
The timeline is longer than you think
Claims take time, and roofing work often waits on approvals.
One customer's project ran roughly eight months from signed agreement to completed roof, held up by insurance delays, then her own circumstances, then her HOA, then weather. She wrote afterward about the follow-through mattering more than the speed.
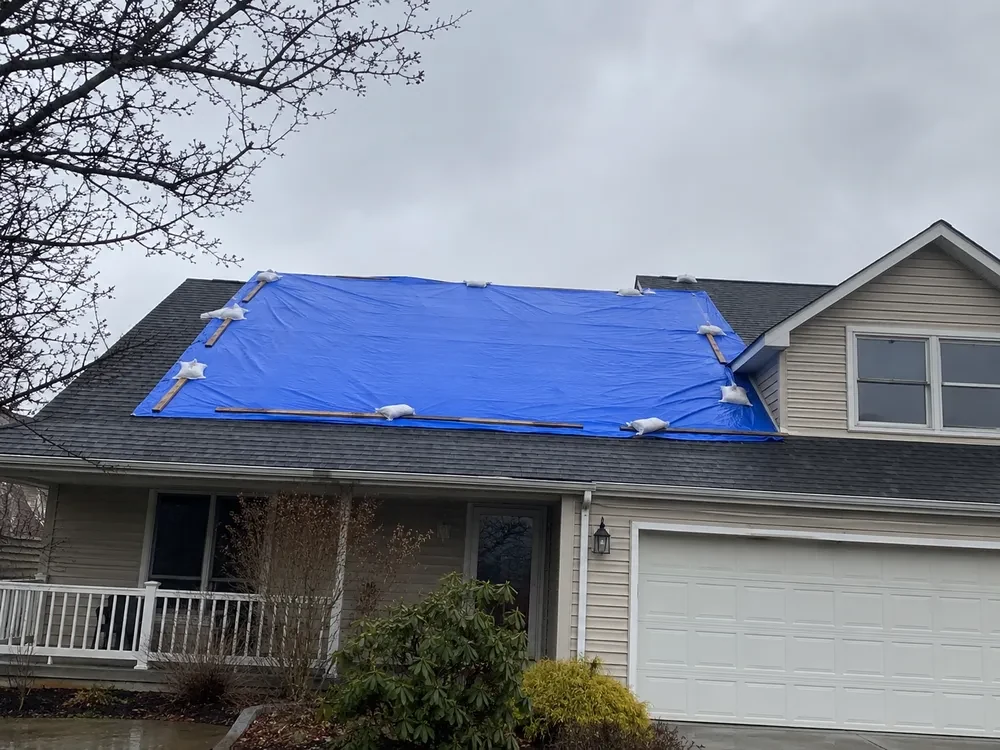
Emergency tarping is a separate matter and should happen immediately. After that February windstorm, we assessed on the 11th and tarped on the 12th, ahead of several days of heavy rain. Tarping protects the interior while the claim gets sorted, and carriers generally expect you to prevent further damage.
A note on honesty
If your roof wore out, insurance is not the answer and no contractor should tell you otherwise.
Roofers who promise to "get your roof covered" or offer to waive your deductible are describing insurance fraud, and it is the homeowner who carries that risk.
If a storm damaged your roof, document it properly and pursue it. If it did not, replacement runs $12,000 to $18,000 for an average home here (5 to 10% higher in Montgomery County and Northern Virginia), and financing is available with terms up to 144 months, subject to credit approval.
---
Hear From Our Customers
May 11, 2026 - I have an Excellent experience with Home Source Roofing from start to finish. John Moye is a very professional, knowledgeable, explained everything clearly and easy to work with. The team arrived on time, and the quality of work was outstanding, especially cleanup was very neat. The whole process was smooth for 1 day job. I'm highly recommend!

Knowledgeable, friendly, did a excellent job in a day, and I would recommend them. I got the architectural shingles rated for 130 mph winds. Less than 3 weeks or so from the time they came out to look, to complete roof installation.

Huge shout out to JR and his crew!!! I can't believe how fast our roof went on and how good it looks! Home source will definitely be my go to from now on. Thanks guys
Home Source Roofing: Local Roofers Delivering Quality Customer Service
Home Source Roofing diligently works with our customers to ensure they are completely satisfied with the roof over their heads. We are proud to offer a variety of roofing services and the experience of our skilled team to the local community. At Home Source Roofing, your peace of mind is our top priority, ensuring that every project we undertake is completed with the utmost attention to detail and the highest standards of safety and efficiency. Choose us for a roofing experience that combines excellence with a personal touch, right here in your neighborhood!
A roof built to last.
Schedule online in under 10 seconds: a thorough inspection, an honest quote, and a roof built to last.